

Introduction: Right-Sizing Your Landed Home in Singapore Retirement
Right sizing in retirement is one of the most powerful financial moves a landed homeowner in Singapore can make – and it doesn’t have to mean giving up the life you love. Selling the landed home to unlock cash is not about downgrading; it’s about deliberately restructuring your largest asset so your property wealth works for you during the decades ahead, rather than sitting locked in walls, land, and rising maintenance costs.
Can you sell your landed home in Singapore to unlock cash without sacrificing comfort, location, and family proximity? Yes – if you plan the sale sequence carefully, understand the net proceeds after CPF refunds and stamp duty, choose a right-sized replacement home in the same district, and deploy freed capital into retirement income streams like CPF LIFE, Singapore Savings Bonds, or T-bills. Planning is essential in executing effective right-sizing without sacrificing living standards. This guide walks you through exactly how.
This article is written for Singapore retirees and pre-retirees aged roughly 50–75 who own a landed private home and want to convert property wealth into accessible liquidity for retirement – without losing daily life quality. It does not cover detailed stock investing strategies, overseas migration, or non-Singapore tax rules. Here’s what you’ll take away:
-
How much cash you can realistically unlock from a landed sale in 2026 (with a worked numerical example)
-
Government schemes – including the Silver Housing Bonus, Lease Buyback Scheme, and Proximity Housing Grant – that put money back in your pocket when right sizing
-
How to choose a right-sized home that keeps you close to adult children, medical care, and community
-
Step-by-step sequencing so you avoid costly ABSD, SSD, or loan-tenure traps
-
How to handle the emotional and family dynamics of leaving a landed property
Understanding Right-Sizing in Retirement for Landed Owners
Right-sizing is not simply moving to a smaller flat. For landed private property owners entering retirement, it is a deliberate, planned restructuring: aligning your home’s size, location, cost base, and accessibility features with your retirement goals, health trajectory, and family needs. At AESTHETIC HAVENS, we view right-sizing as optimising living space and unlocking home equity – not as a concession, but as a strategic upgrade to how your property wealth serves your golden years.
What “Right-Sizing” Really Means When You Own a Landed Home
Right-sizing is the intentional process of moving to a property that fits current lifestyle needs. For landed owners, that typically means selling a multi-storey terrace, semi-detached, or bungalow – often your largest asset, valued at S$3–6 million or more – and purchasing a home that matches today’s mobility, space, and financial requirements. Right-sizing can free several hundred thousand dollars that would otherwise remain illiquid, trapped in land, roof repairs, and property tax obligations.
This is the opposite of panic selling or forced selling during a health emergency. It is a calm, numbers-driven restructuring. Many retired landed owners in Singapore are “asset rich, cash poor”: they sit on multi-million-dollar properties yet lack enough cash for rising medical costs, family support, travel, or even comfortable daily life. Right-sizing solves that gap. The goal is to convert property wealth into accessible liquidity for retirement while preserving the things that actually matter – community, family proximity, and comfort.
Retirement, Lifestyle, and the Singapore Housing Context in 2026
Singapore’s 2026 environment makes right sizing particularly relevant. Medical costs continue to climb, CPF LIFE payouts depend partly on how much sits in your CPF retirement account, and ageing landed estates demand ever-larger maintenance budgets. Landed homes typically carry higher Annual Value (AV), pushing property tax rates to the 32% marginal tier for AV above S$140,000 – a cost that only grows as valuations rise.
At the same time, the government has strengthened policy support for seniors who right-size. The enhanced Silver Housing Bonus – increased from December 2025 – now offers up to S$40,000 when seniors right-size to a smaller flat, with a household income ceiling of S$16,000 monthly. Meanwhile, cooling measures remain active: in July 2025, the Seller’s Stamp Duty (SSD) holding period was extended from 3 to 4 years, with SSD rates increased by 4 percentage points across all tiers. For many Gen X and baby boomer landed owners, 2026–2030 represents a critical window to review their property strategy before health, mobility, or market shifts force a less favourable outcome.
Understanding what you’re really trading – space and land for cash flow, convenience, and services – is the essential first step before you list your landed home.
Unlocking Cash Without Losing Lifestyle: What You’re Really Trading
Selling a landed house is both an emotional and a financial trade-off. You’re exchanging space, land, and the identity of “owning a house” for improved liquidity, lower recurring costs, and often better daily convenience. The key principle is “keeping the lifestyle, changing the address” – same neighbourhood or similar amenities with a smaller, smarter footprint.
From Landed to Right-Sized Living: Space, Access, and Comfort
Typical right-sizing options for landed owners include:
-
Nearby freehold condo or apartment (900–1,200 sq ft): single-level living, lift access, security, pool and gym facilities
-
Central or city-fringe HDB resale flat (3–4 room flat): lower flat price, vibrant community, active hawker centres nearby
-
Senior-focused housing: a 2-room Flexi flat designed with senior-friendly fittings, or a community care apartment with built-in care services and an on-site community manager
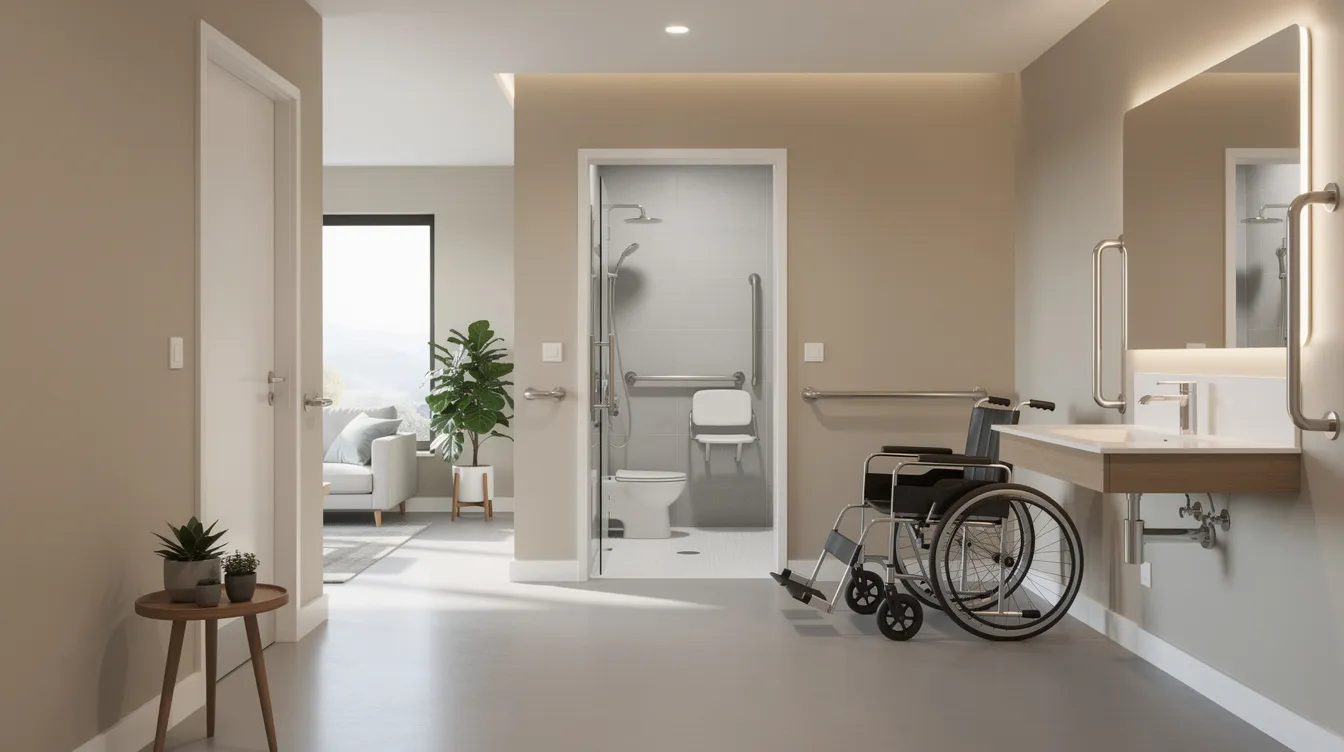
A smaller living space can preserve quality of life while minimizing costs associated with larger properties. Transitioning to a property with amenities can enhance daily living for retirees – pools, gyms, BBQ areas, and landscaped gardens replace the landed owner’s maintenance-heavy private garden. Comfort in retirement means day-to-day ease: no more climbing stairs with groceries, no more weekend roof inspections, lower utility bills from a compact unit, and grab bars in bathrooms when needed. Transitioning to a smaller home helps reduce upkeep and maintenance responsibilities, freeing time and energy for what actually enriches your daily life.
Keeping Location, Community and Family Proximity
One of the biggest fears when right sizing is being uprooted from your neighbourhood. But retirees selling a large landed home in areas like Serangoon Gardens, Thomson, or Bukit Timah can often buy a smaller property in the same or adjacent district. Landed homes in Serangoon’s Mimosa Terrace, for example, transacted at a median of S$4.43 million in the 12 months to March 2026 – while freehold condos in the same district can be found at S$1.5–2.0 million for a well-appointed 2-bedroom unit.
Staying near adult children, grandchildren’s schools, places of worship, preferred polyclinics, and hospitals is a non-negotiable for most retirees. The Proximity Housing Grant provides up to S$30,000 for families purchasing a resale flat to live near or with their parents or children, making this proximity even more affordable. AESTHETIC HAVENS uses a social-anchor mapping approach – overlaying family home locations, commute times, medical facilities, and public transport access – to shortlist right-sized options that keep retirees embedded in their existing community.
The Financial Upside: Liquidity, CPF, Silver Housing Bonus and Investment Options
Selling a landed home can release significant capital tied up in property. The sale proceeds from a S$3.5–4.5M landed sale, after deductions, can yield net proceeds of S$1.6–2.0 million or more in freed cash and CPF balances. This capital can be strategically redeployed:
-
Top up your CPF retirement account to reach the full retirement sum, which can increase CPF LIFE payouts significantly – boosting your guaranteed monthly retirement income for life
-
Build a cash buffer in Treasury Bills, Singapore Savings Bonds, or fixed deposits to cover 10–15 years of expenses
-
Maintain a lump sum emergency fund for unexpected medical conditions or family support
Downsizing typically results in lower ongoing expenses such as property taxes and maintenance fees. Right-sizing can also reduce utility bills and maintenance costs substantially. Monthly expenditure for the average retired household in Singapore is about S$1,970 – and right-sizing puts you well within reach of covering that comfortably from investment returns and CPF LIFE alone, without touching principal.
In short: right-sizing transforms illiquid equity in walls and land into flexible retirement funding while preserving lifestyle anchors. The years ahead become more financially secure, not less comfortable.
How to Plan Your Right-Sizing Journey: From Landed to Lifestyle-Fit Home
Sequencing and exact figures matter enormously when right sizing. A mis-timed sale or purchase can cost tens or even hundreds of thousands of dollars in unnecessary stamp duty, foregone CPF interest, or avoidable renovation costs. AESTHETIC HAVENS works as a neutral real-estate advisory, helping owners model multiple scenarios rather than pushing specific projects or developments.
Step-by-Step Process to Right-Size from a Landed Home
If you’re a landed owner aged roughly 50–75 considering right-sizing within the next 1–3 years, follow this process:
-
Clarify your retirement budget and lifestyle must-haves. Estimate monthly expenses including medical, travel, utilities, and family support. Define non-negotiable requirements: proximity radius around your adult children’s homes, minimum room count, access to public transport, walkable amenities. Maintaining or lowering monthly living costs in retirement can improve financial security – so quantify your targets early.
-
Obtain a realistic valuation of your current landed property. Review URA caveats and recent comparable landed sales in your district. For landed homes, value is often in the land itself – plot size, plot ratio, URA zoning, and redevelopment potential can significantly affect price. A valuation specialist is critical here; don’t rely on online estimates alone.
-
Estimate net sale proceeds after all deductions. Subtract existing loan repayments, CPF refund obligations (including accrued interest on CPF savings used for the property), agent commissions (~2%), legal fees, property tax adjustments, and any repairs needed to make the home saleable. Net proceeds from sold landed properties can be 15–25% lower than the gross sale price after all costs.
-
Define your purchase budget and financing approach for the next home. Decide whether you’ll pay fully in cash or take a small bank loan or HDB loan. Factor in Buyer’s Stamp Duty on the flat purchase or condo purchase price. If you’re over 65, loan tenure and Loan-to-Value limits tighten – MAS regulations mean the LTV drops if the loan extends beyond age 65 or exceeds 30 years.
-
Plan the sale-and-purchase sequence. Selling first gives certainty on cash but means arranging interim housing (short-term rental, serviced apartment, or staying with family). Buying first avoids disruption but may trigger ABSD if you temporarily own two properties. Weigh bridging finance costs against convenience. Total costs of ownership should factor into the decision to ensure ongoing affordability.
-
Execute with clear milestones. Set marketing timelines, manage viewings, negotiate deliberately, and lock in a realistic completion date that aligns with your replacement home’s availability.
Choosing Your Next Home Type: Condo, Apartment, HDB Resale Flat, or HDB
The right-sized home you choose determines both your lifestyle and financial outcomes. Here’s how the main right-sizing options compare:
|
Criterion |
Private Condo/Apartment (e.g. 1,000–1,200 sq ft freehold) |
Central/City-Fringe HDB Resale Flat (3–4 room) |
Senior-Focused Housing (2-Room Flexi / Community Care Apt) |
|---|---|---|---|
|
Typical Price Range |
S$1.5–2.2M |
S$400–700K |
S$100–200K (short lease flats) |
|
Facilities |
Pool, gym, security, concierge |
Hawker centres, void deck, community clubs |
Senior-friendly fittings, grab bars, care services |
|
Accessibility |
Lift, single-level units available |
Lift in newer blocks; older blocks may lack |
Purpose-built for elderly; barrier-free |
|
Ongoing Costs |
Maintenance fees S$300–800/month |
Low town council fees |
Very low fees; subsidised flat pricing |
|
Remaining Lease |
Freehold or 99-year options |
Check remaining lease (critical for CPF usage, HDB loan eligibility) |
Shorter lease (e.g. 15–45 years), matched to youngest owner’s age |
|
Community |
Quieter, self-contained |
Active, multi-generational |
Community care apartment includes on-site community manager |
|
Resale Flexibility |
High, on open market |
Subject to HDB resale rules; resale levy may apply |
More restricted; designed as final home |
A 2-room Flexi flat is designed for seniors with lower costs, and seniors aged 55 and above can buy one directly from HDB. Community care apartments are for seniors aged 65 and above and offer built-in care services – a strong option for those who anticipate needing more support in later years. HDB flat owners moving to a subsidised flat should check whether a resale levy applies based on prior flat type and government schemes used.
For retirees who are also business owners, some may consider redeploying part of their sale proceeds into industrial or commercial property – AESTHETIC HAVENS provides advisory for such clients as well.
Worked Example: Terraced House to Right-Sized Condo in 2026
Let’s walk through a concrete scenario using 2026 data:
The sellers: Mr and Mrs Lim, aged 62 and 60. They own a freehold inter-terrace house in Serangoon, valued at S$3.6 million. No outstanding mortgage. CPF savings used for the original purchase total approximately S$400,000 (including accrued interest).
Sale costs:
-
Agent commission: ~2% = S$72,000
-
Legal fees: ~S$3,000–5,000
-
Minor repairs and touch-ups: ~S$15,000
-
Property tax settlement: adjusted at completion
-
SSD: S$0 (property purchased well over 4 years ago)
-
CPF refund: ~S$400,000 returned to their CPF account (principal + accrued interest)
Net from sale: Approximately S$3.1 million in combined cash and CPF after all deductions.
The replacement home: Freehold 2-bedroom condo, 900 sq ft, in the same district. Purchase price: S$1.7 million. Buyer’s Stamp Duty: approximately S$49,600 (progressive BSD schedule). No ABSD, as the Lims are selling their only residential property before purchasing. Renovation costs for the new unit: ~S$40,000.
Capital unlocked: After the condo purchase and all associated costs, the Lims have approximately S$1.6–1.8 million freed across cash and CPF balances. Right-sizing can unlock several hundred thousand dollars in cash – in the Lims’ case, well over a million.
Monthly retirement income potential: If S$1.5 million is deployed – partly into CPF retirement account top-ups (boosting CPF LIFE payouts), partly into SSBs and T-bills yielding ~3.5–4% – the Lims can generate approximately S$4,500–5,500 per month in combined retirement income, well above the average monthly expenditure for retired households of S$1,970. Their property tax drops dramatically, maintenance shrinks, and they gain lift access, a pool, and a security-managed environment – all while staying in Serangoon, minutes from their adult children.
Selling a high-value home often yields substantial net proceeds after deducting selling costs and mortgages. Home equity can be utilized to enhance retirement income streams through strategic investments. The Lims’ example illustrates how right-sizing can improve flexibility in financial planning and provide cash flow for additional needs.
Navigating Taxes, Rules and Market Risks When You Right-Size
Even experienced private owners must navigate a web of stamp duties, CPF rules, and Loan-to-Value limits when right sizing. Policies shift – cooling measures have tightened repeatedly – so up-to-date professional advice is essential. Capital gains tax implications can affect financial outcomes of selling property in retirement, particularly for those holding multiple assets.
Stamp Duties, Loans and CPF: What Landed and Private Property Owners Need to Watch
Buyer’s Stamp Duty (BSD): Every replacement home purchase triggers BSD on the purchase price. In 2026, BSD is progressive – 1% on the first S$180,000, scaling up to 6% on portions above S$1.5 million. For a S$1.7M condo, expect approximately S$49,600 in BSD.
Additional Buyer’s Stamp Duty (ABSD): If you or your spouse still holds another residential property when acquiring the replacement home, ABSD applies. For Singapore citizens buying a second property, ABSD is 20%. Selling your existing flat or private home first – or within the required disposal window – can help you avoid or reclaim ABSD. Timing the sequence is critical.
Loan-to-Value (LTV) and age-related tenure: If you consider a small mortgage in your 60s, LTV limits may drop to 55% or lower if the loan tenure extends beyond age 65 or if you have existing housing loans. For HDB loans, the maximum tenure is the shortest of 25 years, or 65 minus your average age, or the remaining lease minus certain restrictions. The remaining lease of any HDB flat must cover the youngest owner to at least age 95 for full CPF usage.
CPF refund requirements: When selling your landed home, all CPF savings used for the property – including accrued interest – must be refunded to your CPF account. This is mandatory. While it reduces your immediate cash, it can boost your CPF retirement account balance and increase your CPF LIFE payouts. To withdraw CPF Retirement Account savings for immediate retirement needs, your property must have a remaining lease lasting at least to age 95.
The 15-month wait-out period for private owners purchasing an HDB resale flat has been removed as of July 2026, and seniors aged 55 and above are exempt from a 15-month wait-out period – making the transition from private home to HDB resale flat considerably smoother for retirees.
AESTHETIC HAVENS can help stress-test different sequences – sell first versus buy first – modelling the stamp duty, CPF, and cash-flow impact of each approach.
Market Timing vs Personal Timing
Many landed owners hesitate, waiting for the “perfect” market price. But personal timing almost always matters more than market timing. Moving before major renovations are needed (a new roof, replumbing, or structural repairs on a 30-year-old terrace can run S$200,000+) saves real money. Moving before a spouse’s mobility declines and stairs become unsafe prevents a crisis-driven sale. Moving while you can calmly choose your replacement home – rather than being forced to sell during a downturn because of a health emergency – is its own form of financial discipline.
The landed property market is a niche segment with fewer transactions and longer selling cycles. If your property sits on the open market for 9–12 months in a slower period, your retirement planning timeline shifts accordingly.
Risk Management: Contingency Plans and Interim Housing
Smart right-sizing includes planning for what happens if things don’t go perfectly:
-
Longer-than-expected sale period: Landed segments can take 6–12 months. Budget for this in your timeline and don’t commit to a replacement purchase until your sale has at least reached the Option to Purchase stage.
-
Interim housing if selling first: Options include short-term rental (3–6 months), staying with adult children, or serviced apartments. Factor these costs into your net proceeds calculation.
-
Emergency cash buffers: Avoid locking every dollar into the new home. Keep at least 12–18 months of expenses in liquid form – enough cash to absorb surprises without touching your investment portfolio.
-
Policy changes: Cooling measures, CPF Board rules, and government schemes evolve. What’s true in 2026 may shift by 2027. Build flexibility into your plan.
Investing released home equity can provide a buffer against rising living costs or unexpected expenses – but only if you don’t over-commit to the replacement property.
Common Challenges for Landed Owners Right-Sizing – And Practical Solutions
Even when the numbers clearly favour right-sizing, emotional barriers, family dynamics, and uncertainty about retirement decisions can stall the process. Here are the most common blockers and how to overcome them.
Challenge 1: Emotional Attachment to the Family Home
The family home is where children grew up, where decades of Lunar New Year dinners happened, where the garden was planted tree by tree. Fear of regret is real.
Solutions: Begin with gradual decluttering – months before listing. Host a “farewell gathering” so the home gets a proper send-off. Involve adult children in viewing the new place so they see it as a positive chapter, not a loss. Keep a photographic or video record of the house. Many empty nesters find that once they’ve moved, the relief from maintenance outweighs the nostalgia within weeks.
Challenge 2: Worry About Downgrading Lifestyle or Status
Some retirees feel social stigma about moving from a landed private home to a “smaller” flat or condo. Friends may raise eyebrows.
Solutions: Reframe the move as “optimising” rather than “giving up.” Focus on specific upgrades: lift access, modern facilities, less cleaning, lower utility bills, and more time for travel, grandchildren, and hobbies. Compare the real monthly freedom – S$4,000–5,000 of new retirement income versus weekends spent coordinating plumbers and gardeners. Right-sizing strategies include choosing suitable property features that match lifestyle needs; the replacement home should feel like an upgrade in the ways that matter most in daily life.
Challenge 3: Fear of Making a Costly Mistake
The anxiety of buying the “wrong” right-sized home – or misjudging net proceeds and running short – is legitimate.
Solutions: Run multiple financial scenarios with conservative assumptions. Use independent valuations (not just agent estimates). Line up 2–3 back-up replacement options in case your first choice falls through. Work with an advisor not tied to a single developer or BTO flat allocation – one who can show you exact figures across condo, HDB resale, and 2-room Flexi options side by side. The Lease Buyback Scheme allows cash retention up to S$100,000 for HDB owners who qualify, providing an additional safety net.
Challenge 4: Aligning Spouses and Adult Children
It’s common for one spouse to want to stay while the other wants to move, with adult children holding their own opinions – sometimes about inheritance, sometimes about caregiving convenience.
Solutions: Hold a structured family discussion. Separate inheritance goals from parents’ quality of life – clearly state that the purpose is to improve the parents’ financial security and comfort, not to pre-distribute assets. Agree on non-negotiables first: location radius, minimum space, proximity to specific family members. The CPF housing grant and proximity housing grant can financially reward families who choose to live near each other, aligning incentives for everyone.
Conclusion and Next Steps for Landed Right-Sizing
Right-sizing lets retirees unlock substantial cash from a landed home – often several hundred thousand dollars or more – without sacrificing comfort, location, or closeness to family. It converts your largest asset from a source of rising costs into a foundation of genuine retirement income and daily life flexibility. Right-sizing focuses on optimizing living space and unlocking home equity in retirement, and the 2026 policy environment, with enhanced government schemes like the Silver Housing Bonus (up to S$40,000), the Lease Buyback Scheme, and the removal of the 15-month wait-out for private owners buying an HDB resale flat, makes this the most practical window in years.
Here are your immediate next steps:
-
Audit your current lifestyle and retirement budget. Write down your actual monthly expenses, medical needs, and desired lifestyle for the next 20–30 years ahead.
-
Get a data-backed valuation of your landed property. Use recent URA caveats and comparable sales in your district – don’t guess.
-
Shortlist 2–3 right-sized home types and locations. Consider a private condo, an HDB resale flat in a mature estate, or a 2-room Flexi flat – each with different price, lease, and lifestyle implications.
-
Run a simple net proceeds and monthly cash-flow scenario. Account for stamp duty, legal fees, CPF refund, renovation costs, and ongoing expenses at each replacement home.
-
Schedule a consultation with AESTHETIC HAVENS or a trusted advisor to refine your options, stress-test your numbers, and plan the optimal sale-and-purchase sequence for your situation.
Related topics worth exploring next: monetising spare industrial or commercial units if you’re a retiring business owner, multi-generation housing planning with the proximity housing grant, and estate or legacy structuring tied to property.
Additional Resources: Tools and Guides for Singapore Retirees
Use objective tools and credible information to support your retirement planning journey. Here are resources to build your confidence before making any retirement decisions:
-
Net proceeds worksheet: A simple spreadsheet to estimate what you’ll actually receive from selling your landed home – including CPF refund (with accrued interest), outstanding loans, agent commissions, legal fees, stamp duty, and property tax adjustments. Download or build one before your first advisor meeting.
-
Right-sized home comparison checklist: Score each replacement option on accessibility (lift, grab bars, single-level), distance to family, nearby amenities (hawker centres, parks, clinics), medical care services, and public transport. Weight each factor by what matters most to you.
-
URA zoning and plot ratio explainer: Understanding how zoning affects your current landed property’s value – and the long-term development potential of any target replacement area – helps you negotiate from knowledge, not guesswork.
-
CPF Board retirement planning tools: Use the CPF Board’s online calculators to model how your CPF account balances, full retirement sum top-ups, and CPF LIFE payouts change after right-sizing.
-
AESTHETIC HAVENS guides for business owners: If you’re a retiring business owner considering redeploying some sale proceeds into industrial or commercial property, speak with our team about purpose-built advisory for that age group and situation.
Right-sizing is not about settling for less. It is about making your property wealth serve the retirement you’ve earned – with enough cash, comfort, and community to enjoy every year of it.

