

Introduction
Legal fees for buying private property in Singapore with a private law firm typically range from about S$2,500 to S$4,500 in professional fees alone-before GST and disbursements. That is roughly double what most HDB flat owners pay when purchasing a resale flat through HDB conveyancing channels, where fees are generally lower at S$1,800 to S$2,500. This article breaks down exactly why these costs differ and what you should budget when moving from public to private housing.
Understanding the gap between HDB legal fees and private law firm conveyancing costs matters more than most buyers realise. While legal costs represent a small percentage of purchase price, they form a significant chunk of the upfront costs you must pay in cash before or at completion. Misjudging these figures-especially when upgrading from an HDB flat to a private condo-can throw off your entire cashflow plan at the worst possible time.
In short: HDB resale legal costs usually total S$1,500 to S$4,500 all-in, while legal costs for purchasing private property in Singapore typically range from S$2,500 to S$5,000, driven by more complex title searches, bank panel requirements, and bespoke sale and purchase agreement negotiations. Conveyancing fees typically range from S$1,500 to S$3,500 across both property types, but the extras on the private side push the total higher.
This guide is scoped for Singapore citizens and PRs buying private residential property-condos, apartments, and landed homes-using a bank loan and/or CPF monies. Commercial, industrial, and foreigner-restricted purchases involve different legal requirements and are noted only where relevant.
By the end of this article, you will:
-
Understand what the conveyancing process covers and why every buyer pays legal fees
-
See a side-by-side HDB vs private property fee comparison with concrete numbers
-
Estimate how much cash to set aside for legal and disbursement costs
-
Know when HDB-style fees apply versus when a private lawyer is mandatory
-
Learn cost-saving strategies, including bank subsidies and panel firm selection
Understanding Conveyancing and Legal Fees in Singapore
Conveyancing is the legal process of property ownership transfer-from seller to buyer-and includes registering mortgages, coordinating CPF withdrawals, and ensuring the legal transfer is valid and enforceable. Qualified solicitors must oversee the conveyancing process in Singapore, whether the transaction involves an HDB flat or a private condominium. Every buyer, regardless of property type, must pay some form of legal fees to complete this process.
A critical distinction that trips up first-time buyers is the difference between “legal fees” and “disbursements.” Legal fees are the professional fees charged by a conveyancing lawyer or HDB’s solicitor office for their substantive work-reviewing contracts, drafting legal documents, and managing the transaction. Disbursements are additional costs incurred during conveyancing: third party costs like Singapore Land Authority (SLA) title searches, caveat registration, and administrative fees. Both appear on your final bill, but many advertised quotes show only the professional fee.
Note that AESTHETIC HAVENS provides advisory content and property guidance-not legal services. We work closely with law firms, banks, and CPF advisors, particularly for investors buying private and industrial properties, to help clients anticipate total transactional costs accurately.
What Conveyancing Covers in a Typical Purchase
In a standard property transaction, the conveyancing work begins the moment you receive an Option to Purchase (OTP). Your lawyer reviews the OTP terms, checks for unusual clauses or risks in the sale and purchase agreement, and advises whether to proceed. From there, the firm conducts title searches with the Singapore Land Authority to confirm the seller’s property ownership and identify any existing encumbrances-outstanding loan registrations, caveats, or easements that could affect your rights.
Once you exercise the option, your conveyancing lawyer lodges a buyer’s caveat to protect your interest, coordinates with your bank for mortgage loan documentation, liaises with the CPF Board if you are using CPF monies for the purchase, and prepares the transfer instrument. At completion, the lawyer attends to the exchange of funds, registration of the new title, and confirmation of vacant possession. For private properties, this scope of work is broader than for HDB transactions because of more complex title histories, MCST strata-title obligations, and individually negotiated purchase agreement terms-all of which contribute to higher fees.
HDB vs Private Property Transactions: Why Fees Differ
HDB resale purchases operate within a standardised public-housing framework. HDB provides template documents, uses its own Resale Flat Portal, and publishes fixed Conveyancing Fees Rules that cap what can be charged when HDB acts as solicitor. The result is a predictable, streamlined process with limited scope for variation-and HDB properties typically have lower legal fees than private properties.
Private property transactions are more bespoke and contract-driven. Conveyancing lawyers explain property ownership types before transactions, distinguishing between freehold property ownership (indefinite and inheritable) and leasehold properties, which typically have a duration of 99 to 999 years. Older estates may carry caveats, boundary disputes, or mixed-use zoning that require specialized expertise. Bank-heavy financing structures add mortgage documentation layers. And because law firms set their own rates for legal fees in private property transactions unlike HDB purchases, pricing reflects transaction complexity, property type, and the firm’s risk assessment.
Understanding these structural differences sets up the detailed comparison of fee ranges and cost components that follows.
Core Cost Components of Legal and Conveyancing Fees
Building on the distinction between HDB and private transactions, this section breaks down the four main cost components that determine your total legal bill: (1) professional legal fees, (2) third-party disbursements, (3) CPF-related work, and (4) bank and mortgage documentation costs. The reader should always ask lawyers to separate fees from disbursements in their quotes, because some attractively low advertised prices quietly exclude substantial recurring disbursements and additional costs.
Professional Legal Fees for Buyers
For HDB resale transactions using a private lawyer, professional fees typically sit in the S$1,800 to S$2,500 range for straightforward transactions as of 2025–2026. If HDB acts as solicitor under the Board’s Conveyancing Fees Rules, fees may be lower still, calculated on a sliding scale based on purchase price.
Private property conveyancing fees typically range from S$2,500 to S$3,500 for standard purchases-a resale condo in the S$500K to S$2M band with no title disputes or urgent deadlines. Higher-value private properties lead to higher legal fees due to increased risk for the law firm; for properties above S$3M, professional fees often exceed S$4,500. Legal fees are influenced by the property’s value, financing method, and transaction complexity. All professional fees are subject to 9% GST in Singapore, which adds roughly S$225–S$400 on top of the quoted figure. Higher fees may also apply where senior partner involvement or urgent completions are required.
Disbursements and Government-Related Costs
Disbursements are pass-through charges that your law firm collects on your behalf and pays to government agencies and third parties. These include SLA title searches (approximately S$30–S$50 per search), caveat registration at S$64.45 per caveat, IRAS stamp duty e-filing fees, MCST certificate searches, bankruptcy and company searches, and statutory requisitions. Mandatory government fees include various registration and search fees, impacting overall legal costs.
Disbursements for private property conveyancing generally total between S$500 and S$1,200, depending on property type and the number of searches required. For HDB resale, disbursements tend to be lower-around S$300 to S$600-partly because the HDB resale application fee is modest (S$80 for 3-room and larger flats) and fewer ancillary searches are needed. Ignoring disbursements can easily add S$500 to S$1,000 or more to the initial headline quote, turning an apparently cheap fixed fee into a surprisingly large bill.
CPF and Bank Loan Legal Work
Using CPF funds for property purchases incurs additional administrative fees and legal complexity. Your lawyer must submit CPF Board forms, verify OA balance eligibility, check that the remaining lease meets CPF’s minimum threshold (generally at least 20 years for private properties), and coordinate the refund of accrued interest when selling property later. Some firms charge a separate CPF handling fee; others fold this work into a “package” quote. Either way, CPF-related work is real legal labour and should be accounted for.
When a buyer takes a bank loan, the additional costs include preparing and registering the mortgage deed, lodging a mortgagee’s caveat, and meeting the bank’s panel solicitor requirements. For many condo purchases, loan legal fees run from approximately S$1,500 to S$3,000 if handled separately. However, many banks offer a legal subsidy-DBS, for example, publishes estimated legal fee tables for home loan customers and may subsidise S$2,000 or more of the borrower’s mortgage legal costs. Whether loan legal work is included in your conveyancing quote or billed separately is a critical variable: if your chosen firm is not on the bank’s panel, you may need a second mortgage solicitor, adding significant cost. Always confirm the firm’s panel status before appointment.
Comparing HDB Legal Fees vs Private Law Firm Conveyancing Costs
This section provides a direct side-by-side comparison between HDB-type resale legal fees and private law firm conveyancing costs, including typical ranges, what they cover, and when you might pay more. The comparison assumes a Singapore citizen buying a home for owner-occupation in 2025–2026, with both CPF and a bank loan involved, to keep the scenarios realistic and comparable.
Side-by-Side Cost Comparison (HDB vs Private)
|
Criterion |
HDB Resale Flat (HDB-Type Legal Fees) |
Private Condo (Private Law Firm Fees) |
|---|---|---|
|
Professional legal fee range |
S$1,500–S$2,500 (private lawyer); lower if HDB solicitor under Board scheme |
S$2,500–S$4,500 depending on purchase price band and complexity |
|
Common disbursements (indicative total) |
S$300–S$600 (SLA caveat ~S$64.45, title search ~S$30–50, HDB application fee S$80, admin fees) |
S$500–S$1,200 (title search, caveat, SLA registration ~S$500–S$800, requisitions, courier/admin) |
|
Mortgage / CPF work |
Often integrated for HDB loan; separate ~S$1,000–S$2,500 if bank loan |
~S$1,500–S$3,000 for bank mortgage work; sometimes subsidised by lender |
|
Complexity factors |
Town council checks, standardised HDB forms, predictable timelines |
MCST strata title, freehold vs leasehold checks, negotiated SPA, bank panel requirements |
|
Total estimated legal + disbursement range (straightforward case) |
S$1,800–S$3,000 all-in (private lawyer); lower with HDB solicitor |
S$3,500–S$5,800 all-in for S$1M–S$2M resale condo (professional + disbursement + GST) |
While HDB conveyancing fees are generally lower and more predictable, it is important to keep perspective. For a S$1M to S$2M private condo, the S$3,500 to S$5,800 all-in legal cost is still only a small fraction of the buyer’s stamp duty (BSD), additional buyer’s stamp duty (ABSD), down payment, and renovation costs. Legal fees should be budgeted accurately but should not be the sole deciding factor in choosing between property types.
Worked Example: Upgrading from HDB to a S$1.6M Condo
Consider a family that previously bought an HDB resale flat at S$500,000. Their HDB conveyancing fees came to roughly S$2,000 in professional fees plus S$400 in disbursements-about S$2,400 total, excluding GST.
Now they are upgrading to a private condominium resale priced at S$1,600,000, financing 75% via bank loan and using CPF OA for part of the remainder. Their expected legal costs break down as follows: conveyancing legal fee of approximately S$3,200, loan legal fee of about S$1,800, disbursements around S$700, and GST on fees of roughly S$450-bringing total legal-related cash outlay to approximately S$5,700 to S$6,000 before any bank subsidies. If the bank offers a legal fee subsidy of S$2,000, the net cost drops to around S$3,700 to S$4,000.
This example illustrates how upgrading from HDB to private property more than doubles the legal cost component, especially once mortgage work, disbursements, and GST are factored in. The remaining amount after bank subsidies still represents a meaningful upfront cash commitment that should be included in affordability planning alongside stamp duties, option exercise fee, agent commissions, and moving expenses.
When HDB-Style Fees Still Apply vs When Private Law Firm Is Mandatory
HDB’s own legal department no longer acts for most HDB resale buyers and sellers, but the HDB fee schedule-published via HDB’s portal and referenced on LawNet-remains a common benchmark for public-housing-level pricing. HDB conveyancing fees range from S$1,800 to S$2,500 in most standard cases with a private lawyer, and modestly less under the Board’s own scheme.
For any private property-whether a condo, apartment, landed house, or industrial unit-you must engage a law firm. There is no option to “use HDB legal.” Property status affects legal costs, with resale properties generally costing less than uncompleted properties due to the additional developer-related documentation and progressive payment tracking that new launches require. Most HDB flats are sold on 99-year leasehold terms, while private properties may have leasehold periods longer than 99 years or may be freehold-both of which require different title verification work.
Now that the reader understands average costs and comparisons, the next section details the actual conveyancing timeline, step by step, and when each fee is triggered.
Step-by-Step: Conveyancing Timeline and When Fees Are Due
Understanding the timeline of a private property transaction helps buyers know precisely when various legal fees and disbursements must be paid. This is critical for cashflow planning-particularly for buyers who are selling property simultaneously and need to coordinate sale proceeds with new purchase obligations. The following focuses on a standard private resale condo transaction, noting key differences for new launches only where they affect fee timing.
From Option to Purchase (OTP) to Sale and Purchase Agreement
The process begins when the seller grants you an Option to Purchase (OTP). The Option to Purchase grants exclusive buying rights for 14 to 21 days, during which you pay a 1% option fee to the seller. This is the point at which you should appoint an experienced conveyancing lawyer-not later. Early engagement allows your lawyer to review OTP clauses, flag unfavourable terms, check title, and verify your bank’s panel status before you commit additional funds at the option exercise fee stage (typically 4% of purchase price, payable upon exercising the option).
Some law firms collect a partial retainer upon appointment; others bill in one lump sum closer to completion. Asking about the billing schedule upfront prevents surprise cash calls at inconvenient moments.
Key Legal Milestones and Cash Outflows
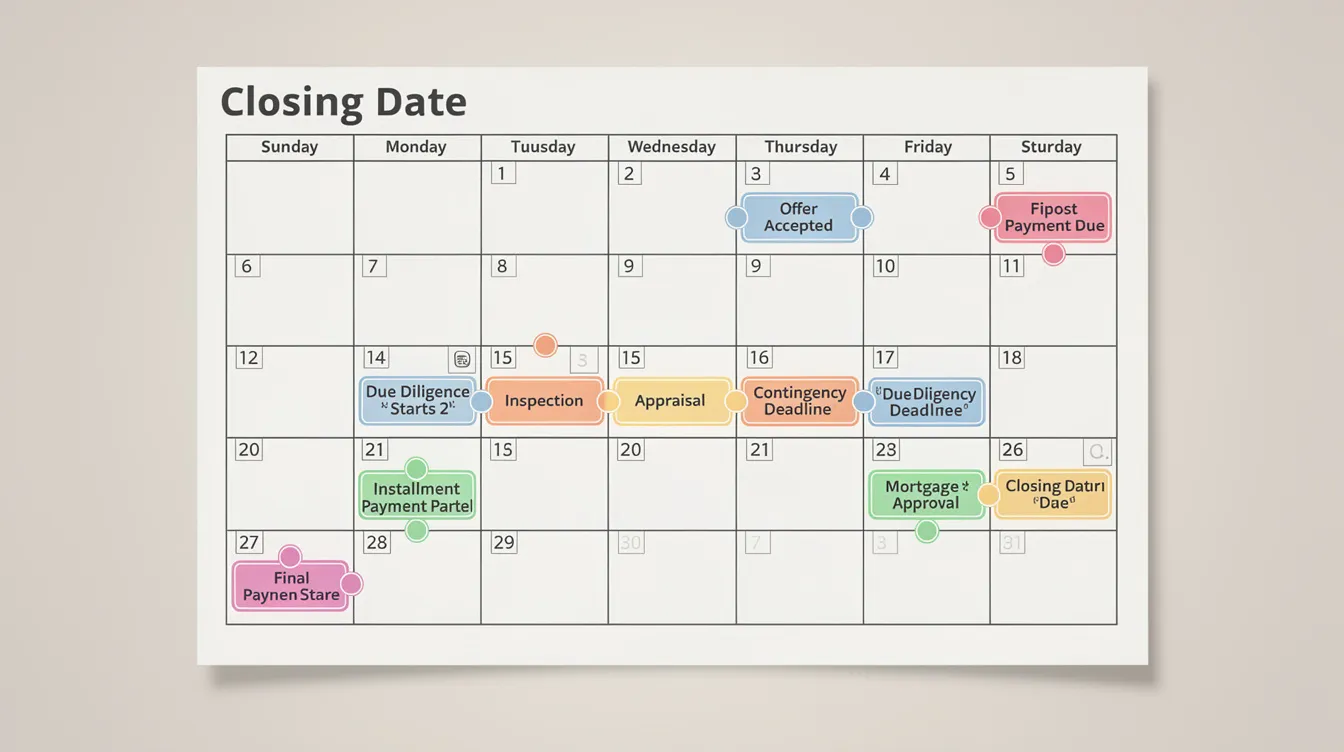
The standard conveyancing timeline from OTP to completion for a private resale condo runs approximately 8 to 12 weeks. Here are the key milestones and when fees are triggered:
-
OTP exercise deadline (usually 14 days) – Legal review fees begin to accrue. Your lawyer confirms terms and you pay the option exercise fee to the seller.
-
Stamp duty payment window (14 days from OTP exercise) – Stamp duty must be paid within 14 days of signing the agreement. Buyer’s stamp duty (BSD) is calculated on the higher of the purchase price or market value. Buyer’s Stamp Duty can reach S$44,600 for a S$1.5M property. Additional buyer’s stamp duty (ABSD) rates vary based on the buyer’s citizenship and number of properties owned. Your lawyer coordinates stamping with IRAS, though stamp duties are a separate statutory cost from legal fees.
-
Caveat lodgement and title searches – Your lawyer lodges a buyer’s caveat (a caveat costs S$64.45 to lodge in Singapore) and conducts title searches. This is the typical disbursement trigger stage.
-
Bank loan documentation signing and mortgage registration – Once the home loan is formally approved, the bank’s panel solicitor (ideally the same firm handling your conveyancing) prepares the mortgage deed and lodges the mortgagee’s caveat. This is often when loan legal fees are charged.
-
Completion date (8–12 weeks from OTP) – Final payment of professional fees, outstanding disbursements, registration fees, and any remaining GST. The seller delivers vacant possession and the legal transfer of title is registered with SLA.
Although some costs can be paid out of CPF monies (such as stamp duties for your first property in certain circumstances), most legal fees require cash upfront, with possible CPF reimbursement later. Seller’s stamp duty, if applicable to the seller, must be paid within 14 days of sale-a separate concern but one your lawyer will flag if you are also selling property concurrently.
What Changes for New Launch Condos or Industrial / Commercial Units
Buying an uncompleted private property from a developer involves a standard developer sale and purchase agreement with prescribed terms, progressive payments tied to construction milestones, and more predictable timelines. This can slightly reduce the legal complexity of SPA negotiation but does not eliminate conveyancing costs-title registration, mortgage work, and CPF coordination still apply. Complex transactions require additional legal work and increase overall costs regardless of property status.
For buyers of industrial and commercial units, additional checks are needed: zoning verification, usage approvals, existing tenancy structures, and sometimes environmental compliance. These special circumstances may push legal fees well beyond the S$4,500 upper range typical for residential private properties. A survey fee may also apply for landed or industrial lots. From AESTHETIC HAVENS’ perspective, investors in strata industrial or shophouse properties should factor in these additional costs early, ideally during the due diligence phase.
The next section surfaces common pitfalls and how to avoid hidden cost blow-ups.
Common Cost Pitfalls and How to Avoid Overpaying
Buyers often fixate on the headline legal fee number and overlook the add-ons, exclusions, and bank/CPF complexities that inflate the final bill. Here are the three most common problems and their solutions.
Problem 1: “Too Cheap” Quotes that Exclude Key Work
Some advertised quotes-say S$1,500 for condo conveyancing-may exclude CPF submissions, loan documentation, or substantial disbursements. The final bill in such cases often lands closer to S$3,000 to S$4,000 once all the hidden costs surface. Legal fees for private property transactions can exceed S$3,500 when the full scope of work is accounted for.
Solution: Always request a written scope of work listing exactly what is included-OTP review, SPA review, CPF Board submissions, loan documentation, disbursements, and GST. Compare quotes on an all-in basis, not just the professional fee line. A true fixed fee quote that bundles everything provides the most reliable budgeting basis.
Problem 2: Not Checking If the Firm Is on Your Bank’s Panel
If your chosen law firm is not on your bank’s panel, the bank may appoint its own mortgage solicitor and charge a separate set of loan legal fees. This can add S$1,500 to S$3,000 to your total cost-money that could have been saved by choosing the right conveyancing lawyer from the start.
Solution: Confirm panel status with your bank before appointing a firm. Many buyers find it most cost-effective to choose a panel firm that can handle both conveyancing and loan work in a single engagement, consolidating fees and reducing coordination headaches. Your real estate agent or mortgage broker can often provide a shortlist of panel firms.
Problem 3: Ignoring CPF Handling and Industrial / Investment Nuances
Investment buyers and business owners purchasing industrial units sometimes assume the same pricing as a simple residential home purchase. But CPF usage limits for properties with shorter remaining leases, zoning checks, complex tenancy agreements, and higher fees for non-standard property types can add meaningful legal work and cost.
Solution: Get a tailored quote when buying strata industrial, shophouse, or mixed-use properties. For investment or business purchases, consulting an advisor like AESTHETIC HAVENS on operational and investment fit at the same time ensures you anticipate total transactional costs-not just legal fees, but also stamp duties, survey fees, and potential renovation costs. Complex property transactions demand specialized expertise that generic quotes rarely cover.
Once these pitfalls are understood, buyers can plan budgets confidently and focus on selecting the right asset.
Conclusion and Next Steps
Legal fees and conveyancing costs are one of the most predictable expenses in buying property in Singapore-yet they remain one of the most frequently misunderstood. HDB conveyancing fees are generally lower and more standardised, reflecting the streamlined nature of HDB transactions. Private law firm conveyancing for private properties sits typically around S$2,500 to S$4,500 in professional fees plus S$500 to S$1,200 in disbursements, reflecting the higher transaction complexity, title risk, and regulatory coordination involved. With GST at 9% and potential mortgage legal work on top, total legal costs for a private condo purchase commonly reach S$3,500 to S$5,800 all-in-more for high-value or complex deals.
Next steps for buyers:
-
Set your property purchase budget to include not just the purchase price and stamp duties but a realistic legal fee allowance of S$4,000 to S$6,000 for private property.
-
Shortlist 2–3 law firms on your bank’s panel and request itemised quotes that include CPF work, loan documentation, disbursements, and GST.
-
Clarify cashflow timing with your lawyer-when retainers, disbursements, and GST are due relative to your mortgage loan drawdown and sale proceeds from any existing property.
-
For investors or business buyers, consult AESTHETIC HAVENS to align property choice, legal structure, and operational needs before committing to a purchase.
Related topics worth exploring include BSD and ABSD planning for Singapore citizens buying a first property versus subsequent purchases, industrial property investment costs, and comparing new launch vs resale private condos from a total-cost perspective.
Additional Resources and Visual Aids
The following references provide up-to-date official data on the costs discussed in this guide:
-
IRAS official pages for Buyer’s Stamp Duty (BSD) and Additional Buyer’s Stamp Duty (ABSD) rates – essential for calculating stamp duties accurately based on market value and citizenship status.
-
Singapore Land Authority (SLA) fee schedule for title searches, caveat lodgement, and registration fees – the source of truth for disbursement costs.
-
HDB Conveyancing Fees Rules via HDB’s portal – useful for HDB flat owners upgrading to private property who want to understand what they previously paid and why private fees differ.
-
CPF Board guidance on using CPF for private property – important for understanding CPF monies eligibility, minimum lease requirements, and the home protection scheme.
Recommended visual aids for planning:
-
A bar chart comparing total typical legal + disbursement cost for HDB resale versus private condo purchases at equivalent price points
-
A timeline infographic showing when each legal fee, disbursement, and stamp duty payment is triggered from OTP to completion
-
An annotated sample invoice breakdown separating professional fees, disbursements, GST, and mortgage legal costs
These visuals should be clean and minimal, helping buyers see at a glance where their money goes and when cash must be available.
Frequently Asked Questions on Legal Fees and Conveyancing Costs
This FAQ addresses the most common specific questions Singapore buyers ask about legal and conveyancing costs when moving from HDB to private property.
How much should I budget for legal fees when buying a S$1M private condo?
For a S$1M private condo, budget approximately S$3,000 to S$4,500 for professional conveyancing fees plus S$500 to S$800 for disbursements, before considering any bank subsidy. Legal fees are influenced by the property’s value, financing method, and transaction complexity. If your bank offers a legal subsidy on the mortgage loan component, your net out-of-pocket cost may drop by S$1,500 to S$2,000. Key variables include your choice of law firm, whether you are using CPF monies, and whether the firm is on your bank’s panel.
Are HDB conveyancing fees really cheaper than private property fees?
Yes. HDB conveyancing fees usually range from S$1,800 to S$2,500 for straightforward transactions, while private property conveyancing fees typically cost S$2,500 to S$3,500 in professional fees alone. The gap widens further once you add disbursements (S$500–S$1,200 for private vs S$300–S$600 for HDB) and mortgage legal work. The reasons are structural: private property transactions involve more complex legal checks, MCST investigations, bespoke SPA negotiations, and higher-value title risk assessments.
Can I use CPF to pay for legal fees and stamp duty for private property?
CPF OA funds can be used to pay buyer’s stamp duty (BSD) and certain conveyancing costs for private property purchases, subject to CPF Board rules-including minimum remaining lease requirements and withdrawal limits. However, most legal fees must initially be paid in cash, with CPF reimbursement processed afterward. The timing gap means you still need sufficient cash on hand at completion. For the most current rules on using CPF monies for stamp duties and legal costs, refer to the CPF Board’s official guidance.
Should I pick the cheapest conveyancing lawyer?
Cost matters, but selecting the right conveyancing lawyer based on price alone is a common mistake. Prioritise these factors:
-
Panel status with your bank – avoiding a second mortgage solicitor can save S$1,500 to S$3,000
-
Clear, itemised scope – the quote should explicitly cover CPF work, loan documentation, all disbursements, and GST
-
Responsiveness and relevant experience – an experienced conveyancing lawyer familiar with your property type (private condos, landed, industrial units) will flag issues early and prevent costly delays
A slightly higher fixed fee from a reputable, panel-listed firm almost always delivers better value than the cheapest quote that excludes critical work.
How can AESTHETIC HAVENS help me beyond legal fee comparisons?
AESTHETIC HAVENS advises on which private or industrial properties fit the buyer’s investment or operational needs, helping clients anticipate total transactional costs-legal fees, stamp duties, valuations, survey fees, and renovation costs-as a unified picture rather than isolated line items. We connect clients with suitable professionals, including conveyancing lawyers on major banks’ panels and mortgage partners, to streamline the property purchase process from due diligence through to completion.

